
Mortgage Retention After a Survey: Why Lenders Hold Back Funds and What to Do
You have your offer accepted, your mortgage approved in principle, and your surveyor has just filed their report. Then the lender comes back with a figure lower than you expected, and a note explaining that they are retaining part of your mortgage until certain works are completed. This scenario — a mortgage retention — is one of the more stressful surprises in the buying process, particularly when you had no idea it was coming.
This guide explains exactly what a mortgage retention is, which survey findings trigger one, how to negotiate or work around it, and what happens if the works do not get done.
Quick answer: A mortgage retention is when your lender withholds part of your loan — typically £1,000 to £10,000 or more — because the surveyor’s report identified defects that affect the property’s value or structural integrity. The retained funds are released once a qualified contractor certifies the works are complete. Retentions are more common than most buyers expect, and the right response depends on how large the retention is and what triggered it.
What causes a lender to apply a mortgage retention?
A mortgage retention is triggered by the valuation surveyor’s report, not the homebuyer survey or building survey you commission independently. The lender’s valuer assesses the property on the lender’s behalf and flags anything that presents a risk to the security of the loan.
Common triggers include:
| Defect type | Typical retention amount | What the lender wants |
|---|---|---|
| Roof nearing end of life or localised damage | £2,000 – £8,000 | Contractor report and repair certificate |
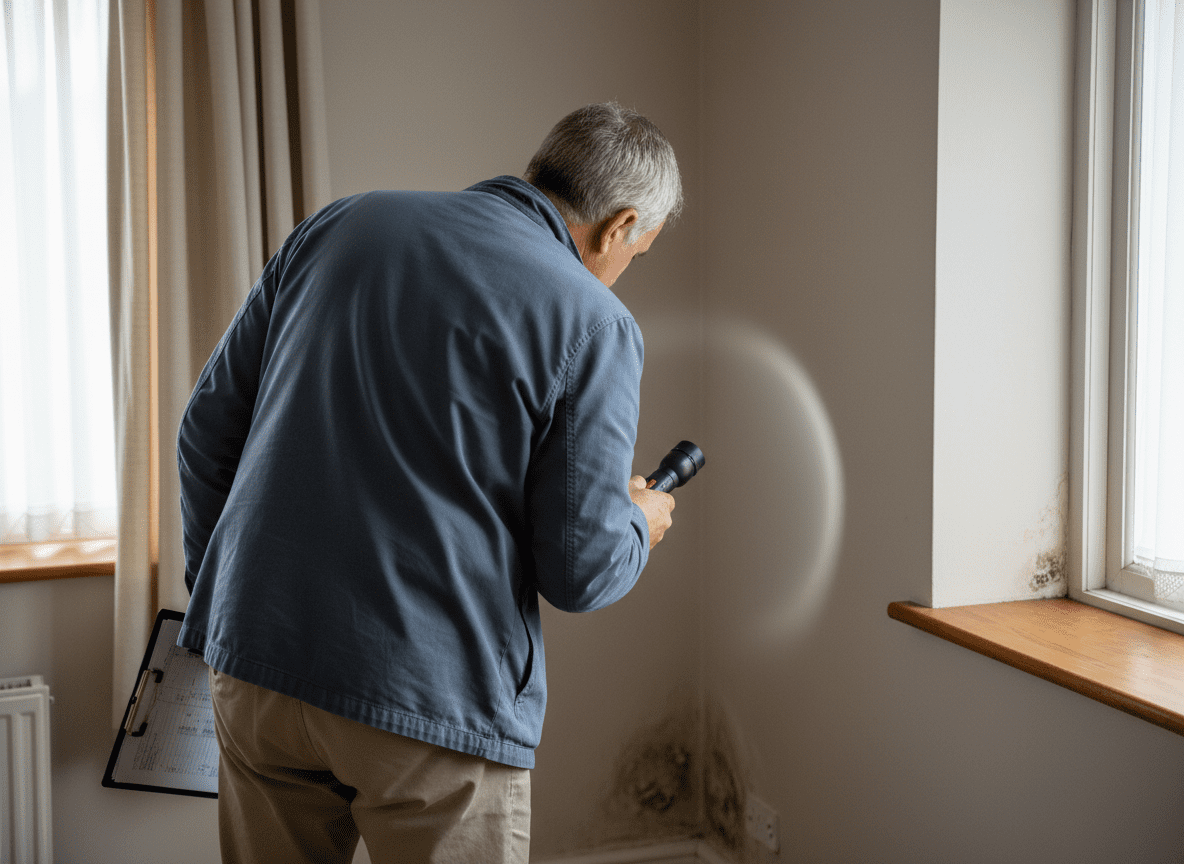
| Active damp penetration or rising damp | £1,000 – £5,000 | Damp survey and treatment with guarantee |
| Significant subsidence or movement cracking | £5,000 – £25,000+ | Structural engineer report and remediation |
| Timber defects (rot, woodworm) | £1,500 – £6,000 | Timber survey and treatment certificate |
| Unsafe electrics or gas installation | £1,000 – £4,000 | EICR or gas safe certificate |
| Japanese knotweed within 7 metres | £5,000 – £15,000 | PCA-accredited management plan and guarantee |
According to Boon Brokers mortgage advisors, many lenders will not apply a formal retention for amounts under £2,000 — instead they may note the issue in the valuation and expect the buyer to deal with it post-completion. Above £2,000 the retention mechanism becomes more likely, and above £5,000 it is almost guaranteed.
How the retention process works in practice
When a retention is applied, your lender releases the loan minus the retained amount at completion. You receive less than expected, which means you need to cover the gap from savings or negotiate with the seller to reduce the price accordingly.
The retained funds are then released in one of two ways:
- Single release: All the retained funds are released once the works are certified complete. This is the most common approach for straightforward defects.
- Stage release: For larger projects such as subsidence remediation or full rewires, the lender may release funds in stages as each phase is certified. This is less common but protects the lender during longer repair windows.
The certification requirement matters. Most lenders want a sign-off from a qualified contractor, not just a receipt for work done. For structural issues this typically means a structural engineer’s completion certificate. For damp, a specialist guarantee from a PCA-accredited contractor. For electrics, an Electrical Installation Condition Report signed by a registered electrician. Check the exact requirement with your lender before commissioning any work.
The timeline from retention to release is usually 7 to 14 working days once the lender receives the required paperwork, though this varies by lender. The works themselves may need to be completed within 3 to 12 months of completion, depending on the lender’s terms. If you miss the deadline, contact the lender proactively — most will extend on request rather than take more drastic action.
Re-inspection costs money
Some lenders send their own surveyor back to verify the works before releasing the retention. Budget £120 to £200 for a re-inspection fee, which is typically charged to you. Confirm whether a re-inspection is required before you instruct contractors, so you are not surprised by an additional cost at the end.
Negotiating around a retention
A mortgage retention gives you three options: fund the gap yourself, renegotiate the purchase price, or walk away. Which one makes sense depends on the severity of the defect and your relationship with the seller.
Renegotiating on price is the most common approach when the retention is triggered by a genuine defect the seller did not disclose. The logic is clear: if the lender has identified a problem that costs £4,000 to fix, the property is effectively worth £4,000 less than you agreed to pay. Most sellers would rather accept a reduced price than have the sale fall through.
Understanding your home survey is the starting point here. If you have had an independent Level 2 or Level 3 survey carried out, you will have independent evidence of the defect and its likely cost of repair — which strengthens your negotiating position considerably compared to relying on the lender’s brief valuation note alone.
If you are considering renegotiating, get a couple of contractor quotes before going back to the seller. A firm figure is harder to argue with than an estimate, and it shows you have done the work rather than just looking for a discount.
Our guide on negotiating house price after a survey sets out how to approach these conversations without derailing the sale, and what to do if the seller refuses to move.
What if you cannot fund the retention gap?
The retained amount comes straight out of the funds available at completion. If your deposit calculation was tight, a retention of £3,000 to £5,000 can genuinely put completion at risk unless you have reserves or the seller reduces the price.
A few options worth knowing:
- Ask the seller to contribute. The seller can reduce the agreed price, or agree to pay an amount at completion toward the works via the solicitor. Both approaches achieve the same financial result.
- Use short-term finance. Buyers occasionally use bridging finance to cover a retention gap, though the cost and complexity usually make this a last resort.
- Ask the lender to waive the retention. If you can provide contractor quotes and evidence that works are already in progress, some lenders will waive a small retention rather than apply it. This is not guaranteed, but worth asking your broker to explore.
The broader lesson for buyers who have not yet had their survey: commissioning an independent Level 2 or Level 3 survey before exchange means you find out about significant defects before the lender’s valuer does. That gives you time to negotiate, get quotes, or reconsider — rather than discovering a retention problem days before completion when your options are far more limited.
Frequently asked questions
Does a mortgage retention mean the property is unsafe to buy?
Not necessarily. A retention means the lender has identified a defect that affects the value or security of the property in its current state. Many retention triggers — old roofs, minor damp, dated electrics — are common in older housing stock and are perfectly repairable. The retention is a financial mechanism, not a sign the property is unmortgageable.
Can I use the retained funds to pay for the repairs?
No. The retained funds are held by the lender until the works are certified complete. You need to fund the repairs separately — either from savings or by negotiating a reduction in the purchase price to cover the cost.
What happens if the works are never completed?
The lender holds the retained funds indefinitely until the release conditions are met. If you sell before the works are done, the retention will add complexity to the sale. Most lenders will not pursue legal action over an unreleased retention unless the defect has worsened materially. That said, completing the works and claiming the release is always the right outcome — it is your money.
Is a mortgage retention the same as a down-valuation?
No, they are different outcomes from the same valuation. A down-valuation means the lender values the property below the agreed purchase price, reducing the total loan they are willing to offer. A retention means the lender agrees with the purchase price but withholds part of the loan pending remedial works. You can have one without the other, or both at the same time.
Concerned about what a survey might find — or already dealing with a retention? Blue Blossom Surveys provides independent RICS Level 2 and Level 3 building surveys across Peterborough, Cambridgeshire, Rutland and surrounding areas. An independent survey gives you the full picture before the lender’s valuer does. Get in touch to book.





0 Comments