
The government’s own flood risk service is unusually blunt about its limits. Before you start, it tells you plainly that it will not tell you how likely it is that an individual property will flood, and it will not cover flooding from sources such as blocked drains and burst pipes.
That single caveat is the whole reason buying a house in a flood risk area needs more than a postcode check. The map describes an area. You are buying a building. Those are two different questions, and only one of them is answered by a website.
Key takeaways
- A RICS home survey does not produce a flood risk rating — that comes from the environmental search your solicitor commissions.
- What a surveyor does give you is evidence of how the building has actually behaved: tide marks, replaced floors, patched brickwork, damp at low level.
- The GOV.UK flood service is area-level by design and says so up front.
- The Environment Agency will send you a flood history report for an address, usually within 20 working days — ask early, because that timescale eats into a conveyancing chain.
- On a low-lying property with any history, a Level 3 survey is usually the sensible choice.
Does a Home Survey Check Flood Risk?
No — not in the sense most buyers mean. A RICS home survey does not produce a flood risk score or search the Environment Agency’s datasets. Flood risk data reaches you through the environmental search your solicitor commissions during conveyancing. What the survey adds is different and, in a flood risk area, arguably more useful: physical evidence of what water has already done to this specific building.
Buyers routinely conflate the two and end up with neither. They see a reassuring flood map, skip the environmental search detail, and book the cheapest survey available. Then the report comes back describing damp at low level and a suspiciously new solid floor, and nobody has connected the dots.
What the GOV.UK Flood Service Actually Tells You
The Environment Agency’s long term flood risk service is free, quick and genuinely worth running before you offer. It covers an area’s long term risk from rivers and the sea, from surface water, from reservoirs, and from groundwater where the data exists. It also shows how climate change might increase the chance of flooding.
What it deliberately does not do is model your house. The service states before you start that it cannot tell you how likely an individual property is to flood. It also excludes flooding from blocked drains and burst pipes, which are among the most common causes of water damage inside a home.
So treat the result as a filter, not a verdict. A clean area rating does not mean the property is dry. A flagged area does not mean the property is uninsurable. Both outcomes should change what you ask your surveyor to look at, not whether you bother having one.
A point most guides skip: surface water flooding — rain arriving faster than drains can shift it — is a completely separate risk from river flooding, and it can affect properties nowhere near a watercourse. If the area rating is driven by surface water, the drainage on the plot matters more than the distance to the river.
Getting the Flood History for a Specific Address
This is the step almost nobody takes, and it is the one that closes the gap between the area map and the building. You can email the Environment Agency with the full address and postcode and request the flood history for the area around that property.
Two practical caveats. The Environment Agency does not hold flood records for every area in England, so a nil return is not proof of a dry history. And the report is sent by email within 20 working days — a month of a conveyancing timeline. Request it the week your offer is accepted, not the week before exchange.
Your lead local flood authority, obtainable through the local council, and the Internal Drainage Board where one operates, are both worth contacting as well. In heavily drained landscapes the drainage board often knows far more about local water behaviour than any national dataset.
What a Surveyor Can See That a Map Cannot
This is where a survey earns its fee on a property in a flood risk area. A map cannot walk into the hall and notice that the skirting has been renewed to exactly the same height on every ground floor wall. A surveyor can.
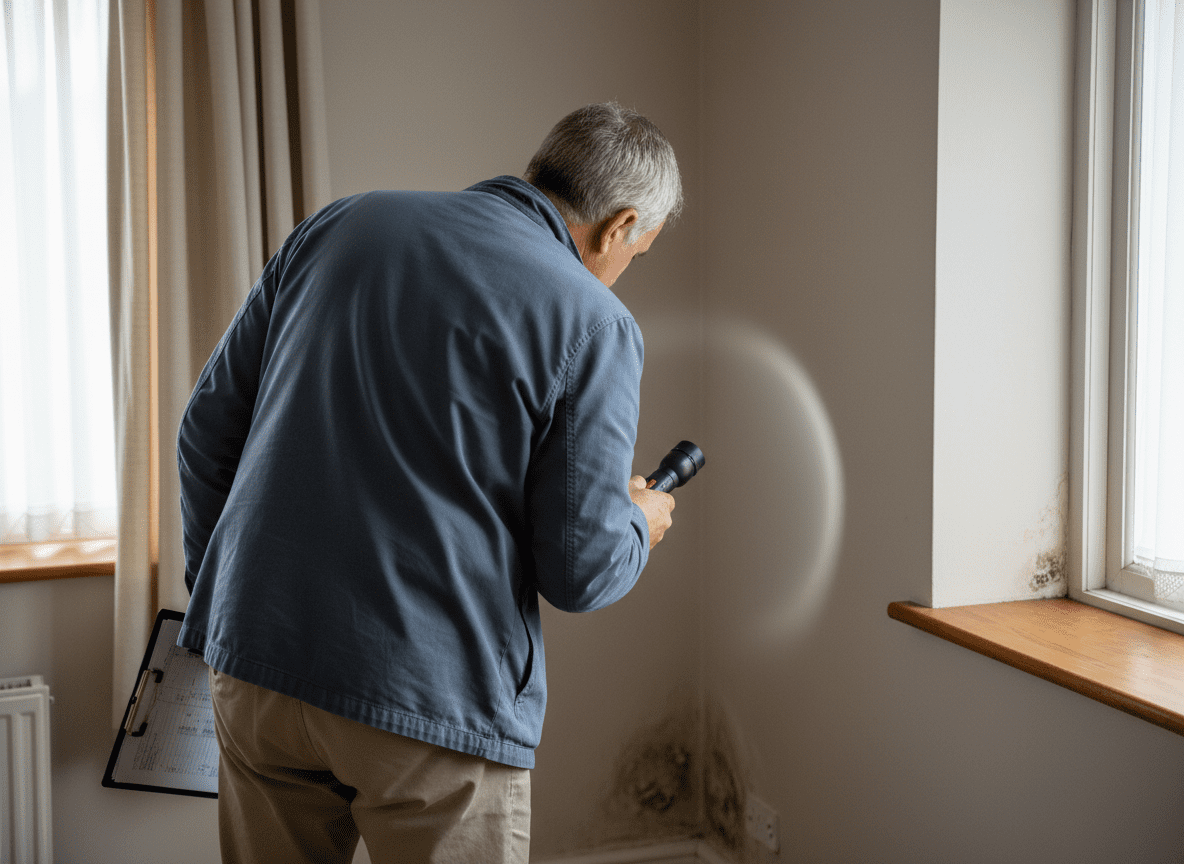
Typical physical evidence of past water ingress includes:
- A horizontal tide line on external brickwork or internal plaster, often faint, often painted over
- Replastering to a consistent height across several ground floor rooms — a strong tell, because ordinary damp repairs are patchy, not uniform
- A modern solid floor in an otherwise period property, or new floor coverings in only the ground floor rooms
- Elevated moisture readings at low level on walls that are otherwise sound higher up
- Airbricks blocked, raised or unusually numerous, suggesting past problems with a suspended timber floor
- Repointing or brick replacement in a band near ground level, sometimes with visible salt staining
- Flood doors, non-return valves or a sump pump already fitted — helpful mitigation, but also a clear signal of history
None of these individually proves the house has flooded. Read together, and set against the environmental search and the Environment Agency history, they build a picture. That triangulation is the actual work, and it is why a report from someone with no stake in the sale is worth having.
Level 2 or Level 3 in a Flood Risk Area?
When a Level 2 is enough
A RICS Level 2 Homebuyer Survey suits a conventional, reasonably modern property in good visible order where the flood risk rating is low and there is no history to investigate. It will still record damp readings, note evidence of past water ingress and flag anything requiring further investigation with a condition rating.
When to step up to a Level 3
A RICS Level 3 Building Survey is the better choice where the property is older, has been altered, sits low relative to the road or the watercourse, or where the search or the seller has disclosed any flooding history.
The Level 3 goes further into construction detail and, critically, discusses causes and likely remedial work rather than simply rating condition. On a property that has taken water before, understanding why and what was done about it is the entire question. If you want a fuller comparison, our guide to choosing between a Level 2 and a Level 3 survey covers the decision in detail.
What to Sort Out Before You Exchange
Exchange is the point of no return. Everything below belongs before it, not after.
- Run the free area check and note which source of flooding is driving the rating — rivers, surface water, reservoirs or groundwater
- Request the Environment Agency flood history early, allowing for the 20 working day turnaround
- Read the environmental search properly with your solicitor rather than skimming the summary line
- Get an insurance quote before you commit, not after — and get it in writing, with the excess stated
- Ask your surveyor to comment specifically on evidence of past water ingress and on existing flood mitigation
- Ask the seller directly whether the property has flooded and whether any claim has been made
- Check the drainage — surface water problems are often drainage problems. Our guide to what a home survey checks about drains explains where the survey stops and a specialist investigation begins
If the survey does turn something up, you have options short of walking away. Our guide to what to do when a home survey reveals problems sets out the realistic routes — renegotiate, require remediation, or withdraw before exchange.
Buying in the Fens and the Low-Lying East
Much of the area we cover is drained landscape. Peterborough, the Fens around Wisbech and Whittlesey, the land either side of the Welland near Spalding, and the villages along the Nene are all shaped by managed water. That is not a reason to avoid buying there. Millions of people live perfectly comfortably in exactly these places.
It is a reason to be specific. In drained landscapes the meaningful questions are local: which drainage board covers the plot, how the property sits relative to the road and the nearest drain, whether the ground floor has been altered, and what the immediate neighbours experienced. National maps flatten all of that into a colour.
We inspect properties across Peterborough, Cambridgeshire, south Lincolnshire, Rutland and Northamptonshire, and low-lying ground is ordinary here rather than exotic. If you have a flood rating you do not understand, tell us before the inspection so we can look properly at the things that matter.
Buying a property where flood risk is a question mark? Talk to Blue Blossom Surveys about a RICS Level 2 or Level 3 survey. We are independent of the sale, we will tell you plainly what the building shows, and we will explain what it means before you exchange.
Frequently Asked Questions
Will a survey tell me if a house has flooded before?
Not definitively, but it will tell you a great deal. A surveyor records physical evidence — tide marks, uniform replastering at a consistent height, replaced ground floor coverings, elevated low level moisture readings, existing flood mitigation. Combine that with the environmental search and an Environment Agency flood history request and you get a reliable picture.
Can I get a mortgage on a house in a flood risk area?
Usually yes. Lenders assess flood risk case by case and generally focus on whether buildings insurance is obtainable at a normal premium. The practical order is to get a written insurance quote first, then talk to your lender or broker, because insurability is what tends to drive the decision.
Does the flood map tell me about my specific house?
No. The GOV.UK service states before you start that it does not tell you how likely it is that an individual property will flood. It is an area-level assessment. It also excludes flooding from blocked drains and burst pipes.
How long does an Environment Agency flood history report take?
The report is sent by email within 20 working days of your request. That is roughly a calendar month, so request it as soon as your offer is accepted rather than close to exchange.
Is a Level 3 survey worth it just because of flood risk?
Where there is any history, any visible alteration to the ground floor, or the property is older or sits low, yes. The Level 3 discusses causes and remedial work rather than only rating condition, and on a property that has taken water that distinction is the whole point.
Written and reviewed by the surveying team at Blue Blossom Surveys Ltd, RICS-regulated residential surveyors covering Peterborough, Cambridgeshire, south Lincolnshire, Rutland and Northamptonshire. Published 6 October 2026. Last updated 6 October 2026.




0 Comments